Is Your “Other Structures” Coverage Enough?
Most homeowners policies limit Other Structures (Coverage B) to about 10% of your dwelling limit. Here is why that may not be enough for detached garages, sheds, guest houses, and fencing.
 Andrew KoehnekeSep 1, 2026
When reviewing your homeowners insurance, it's easy to focus on the coverage for the house itself. But what about the other structures on your property?
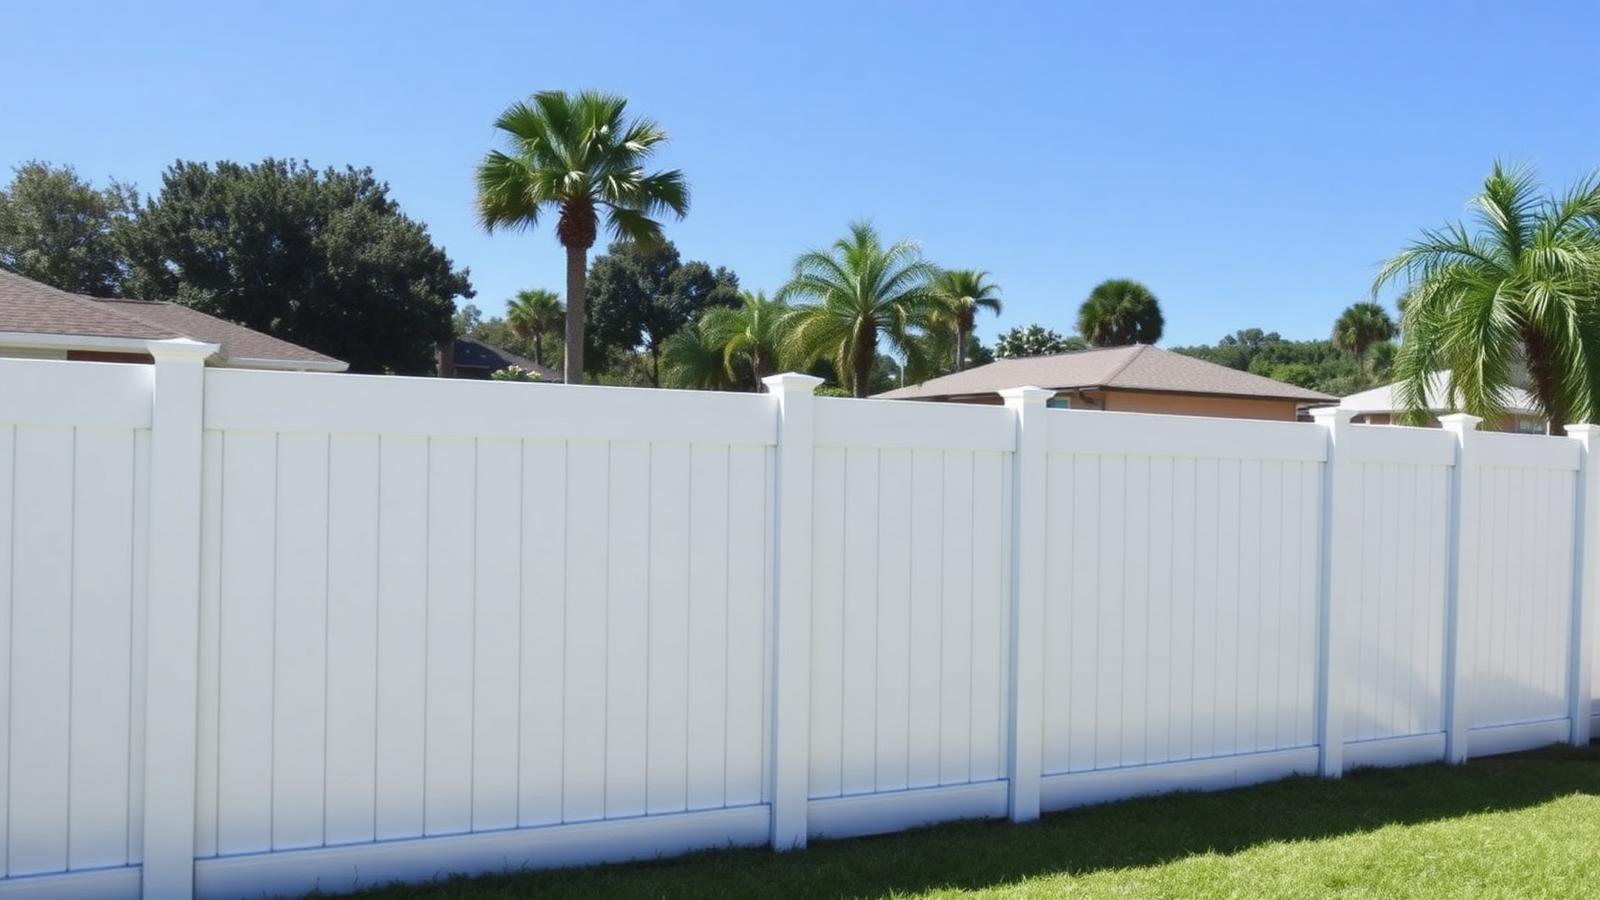
Most homeowners policies include Other Structures Coverage, also known as Coverage B. This coverage is designed to protect structures on your property that are separate from your main home, such as detached garages, storage and tool sheds, guest houses, gazebos and pergolas, fences, pool houses, and certain other permanent structures.
The Standard Coverage May Not Be Enough
Many homeowners policies automatically set Other Structures Coverage at approximately 10% of the dwelling coverage limit, although the actual amount depends on your specific policy.
For example, if your home has $500,000 in dwelling coverage, your policy might provide $50,000 in Other Structures Coverage.
That may sound like plenty, but consider what it would cost to rebuild everything on your property after a major loss.
A large detached garage, finished workshop, guest house, extensive fencing, or other high-value structure could quickly exceed the standard limit. And remember, the Coverage B limit generally applies across the covered detached structures on the property, rather than providing a separate limit for each one.
Take a Look Around Your Property
Ask yourself a simple question: if my detached structures were seriously damaged or destroyed today, would my current coverage be enough to rebuild them?
If you've added a detached garage, shed, guest house, outdoor structure, or made significant improvements since purchasing your policy, it's worth reviewing your coverage.
Construction costs also change over time. A coverage limit that made sense several years ago may no longer reflect today's replacement costs.
Talk to Your Insurance Agent
Don't assume the standard amount included with your homeowners policy is enough for your property.
Review the Other Structures or Coverage B section of your policy and talk with your insurance agent about the structures you have and what they could cost to replace. Depending on your policy and insurance carrier, you may be able to increase your Coverage B limit to better reflect your property's needs.
A quick coverage review today could help prevent an expensive coverage gap when you need your insurance most.
Watch the quick video: Is Your Other Structures Coverage Enough?
Coverage varies by insurance company and policy. Always review your policy documents and speak with your insurance professional to understand your specific coverage, limits, exclusions, and deductibles.