Everything You Need to Know About Florida Home Insurance
A plain-English guide to Florida homeowners insurance: what a policy covers, how hurricane deductibles work, why wind mitigation and 4-point inspections matter, flood coverage, and what actually drives your premium.
 Andrew KoehnekeAug 28, 2026
Florida home insurance can feel complicated, especially for homeowners trying to understand rising premiums, hurricane deductibles, inspections, flood coverage, and the different factors insurance companies consider when deciding whether to insure a property.
At Insurance Specialists of Southwest Florida, we work with homeowners throughout Southwest Florida to help make the process easier to understand. Whether you are purchasing a new home, renewing an existing policy, or simply reviewing your current coverage, knowing how Florida homeowners insurance works can help you make a more informed decision.
What Does Homeowners Insurance Cover?
A typical homeowners insurance policy provides several different types of protection.
Dwelling coverage helps protect the physical structure of your home from covered losses. Other structures coverage may apply to things such as detached garages, fences, or sheds. Personal property coverage helps protect belongings inside the home, while liability coverage can provide protection if you are legally responsible for injury or property damage to someone else.
Policies may also include loss of use coverage, which can help with additional living expenses if your home becomes uninhabitable because of a covered loss.
The exact coverage, limits, deductibles, and exclusions vary by insurance company and policy, which is why it is important to review the details rather than comparing policies based on price alone.
Hurricane and Wind Coverage in Florida
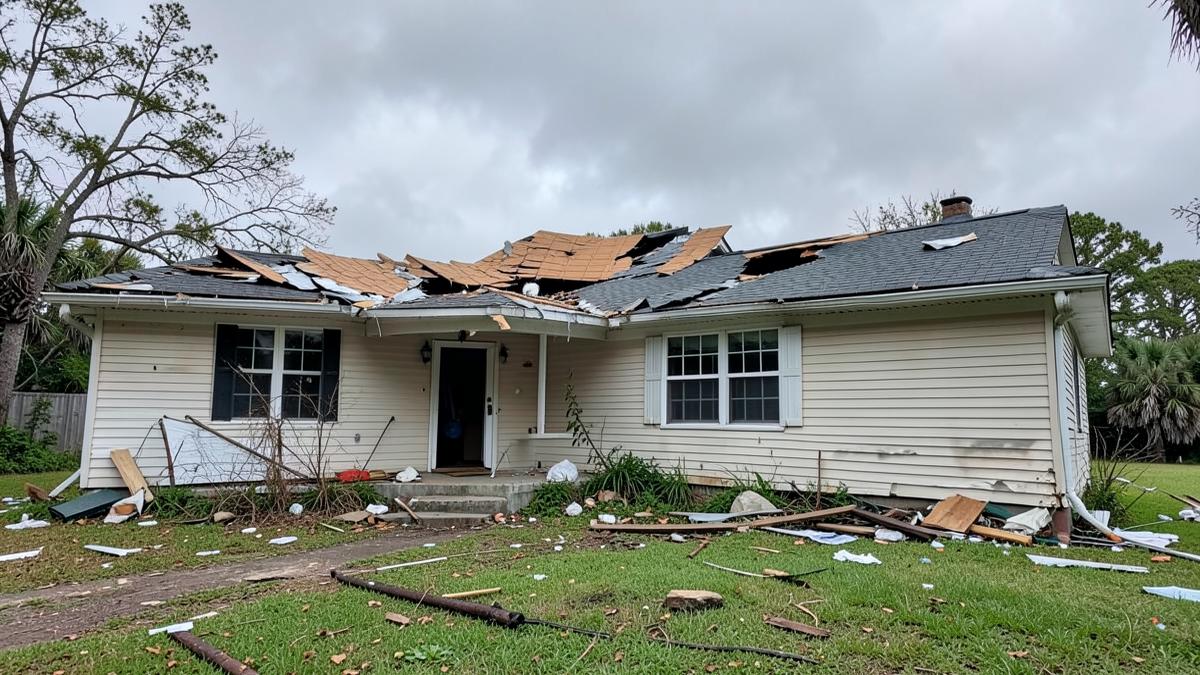
Living in Florida means hurricane and wind exposure are major considerations when purchasing homeowners insurance.
Many Florida policies include a separate hurricane deductible. Unlike a standard flat deductible, hurricane deductibles are commonly calculated as a percentage of the home's insured dwelling value.
That can make a significant difference in how much a homeowner would be responsible for paying after a hurricane loss.
Wind coverage can also vary depending on the insurance carrier and the property's location, so homeowners should confirm exactly how wind and hurricane losses are handled under their policy.
Why Wind Mitigation Inspections Matter
A wind mitigation inspection evaluates features of a home that may help it withstand high winds.
The inspection may document items such as roof shape, roof-to-wall connections, roof deck attachment, secondary water resistance, opening protection, and building code compliance.
Depending on the home's construction and available insurance credits, qualifying wind mitigation features may help reduce the cost of homeowners insurance.
For Florida homeowners, having an up-to-date wind mitigation inspection can be particularly valuable when shopping for coverage.
What Is a 4-Point Inspection?
Another common inspection in the Florida insurance market is the 4-point inspection.
Rather than evaluating the entire property like a traditional home inspection, a 4-point inspection focuses on four major systems: roof, electrical, plumbing, and HVAC.
Insurance companies may request a 4-point inspection, particularly on older homes, to better understand the condition and age of these systems before offering coverage.
An issue identified on a 4-point inspection does not necessarily mean a home cannot be insured, but it may need to be repaired or evaluated before certain carriers will consider the property.
Homeowners Insurance Does Not Automatically Include Flood Insurance
One of the most important distinctions for Florida homeowners is the difference between homeowners insurance and flood insurance.
Standard homeowners policies generally do not cover flooding caused by rising or accumulating surface water. Flood insurance is typically purchased separately.
This distinction is especially important in Southwest Florida, where properties can face storm surge, heavy rainfall, and other flood exposures.
Even homeowners who are not located in a high-risk flood zone may want to discuss whether separate flood coverage makes sense for their property.
What Determines the Cost of Florida Home Insurance?
There is no single price for homeowners insurance. Insurance companies consider many characteristics of both the homeowner and the property.
Common factors can include location, replacement cost of the home, year built, roof age and type, construction type, wind mitigation features, electrical and plumbing systems, prior claims, deductible selections, coverage limits, distance from the coast, and the availability of insurance carriers.
Because each carrier has its own underwriting guidelines and pricing, two companies may evaluate the same home very differently.
The Cheapest Policy Is Not Always the Best Policy
Price is important, but it should not be the only consideration when comparing homeowners insurance.
A lower premium may come with higher deductibles, lower limits, different exclusions, or reduced coverage.
When reviewing quotes, homeowners should consider both the premium and what they are actually receiving for that premium.
Understanding your dwelling limit, deductibles, personal property coverage, liability protection, water-related exclusions, roof settlement provisions, and optional endorsements can help prevent surprises later.
Why Work With an Independent Insurance Agency?
An independent insurance agency can typically work with multiple insurance companies rather than representing only one carrier.
That allows an independent agent to compare different options based on the characteristics of your home and your individual insurance needs.
This can be particularly valuable in Florida, where carrier underwriting requirements and availability can change frequently.
At Insurance Specialists of Southwest Florida, our goal is not simply to provide a quote. We want our clients to understand their coverage and feel comfortable with the protection they are purchasing.
Have Questions About Your Florida Home Insurance?
Whether you're buying a home, approaching your renewal, or simply wondering whether your current coverage still makes sense, reviewing your policy with an experienced insurance professional can help identify potential gaps and opportunities.
Insurance Specialists of Southwest Florida, 12870 Trade Way Four, Suite 108, Bonita Springs, FL 34135. Call 239-949-7717 or email service@fl-ins.com.
If you'd like to learn more, watch our full video, Everything You Need to Know About Florida Home Insurance, where we walk through these topics in greater detail.
Coverage, eligibility, pricing, and underwriting requirements vary by insurance company and individual risk. This article is provided for general informational purposes and is not intended to modify or replace the terms of any insurance policy.